The Supply Chain That Connects Everything
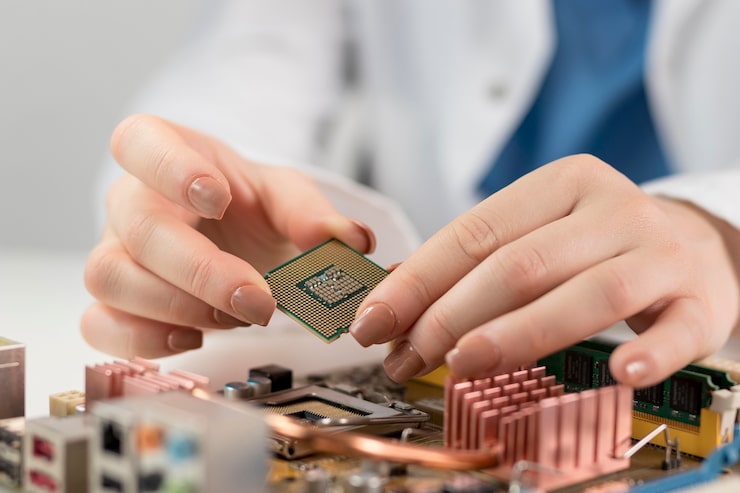
The semiconductor supply chain is one of the most complex and geographically concentrated manufacturing networks in human history. The chips that power every smartphone, laptop, car, appliance, and industrial machine require: ultra-pure silicon (largely from Japan and Germany), specialised chemicals from dozens of countries, equipment that can only be made by a handful of companies globally (notably ASML in the Netherlands for EUV lithography), and fabrication at facilities so technically demanding that only a few organisations can build and operate them — primarily TSMC in Taiwan, Samsung in South Korea, and Intel in the US.
The 2020–2022 global chip shortage — when automotive manufacturers shut assembly lines for lack of microcontrollers, consumer electronics had months-long waitlists, and the economic impact measured in hundreds of billions of dollars — revealed the fragility of a supply chain that had been optimised for cost efficiency over resilience. Understanding why this fragility exists and what’s being done about it explains both the shortage’s persistence and the current geopolitical dimensions of semiconductor policy.
Why the Supply Chain Is This Concentrated
Semiconductor manufacturing has concentrated for economic reasons that are difficult to reverse: building a leading-edge chip fabrication facility (fab) currently costs $20–$30 billion, requires decades of accumulated process knowledge and skilled workforce development, needs an ecosystem of specialised suppliers and service providers nearby, and produces equipment so precise that it takes years to reach full production capacity. These characteristics create enormous barriers to entry that concentrate production in a few highly skilled, well-capitalised locations.
Taiwan’s TSMC manufactures approximately 90% of the world’s most advanced semiconductors (those at 3nm and below as of 2026) — a concentration that creates both supply chain fragility (any disruption to TSMC production affects virtually every technology product) and geopolitical sensitivity (Taiwan’s status vis-à-vis China makes this concentration a significant strategic concern for governments worldwide). No other location currently has TSMC’s process technology advantage or production capacity at the leading edge.
The Government Response: CHIPS Acts and Subsidies
The US CHIPS and Science Act (2022, $52 billion for semiconductor research and manufacturing incentives) and the EU Chips Act (2023, €43 billion) represent major government interventions to diversify semiconductor production away from East Asia. Intel’s fabs in Ohio and Germany, TSMC’s fabs in Arizona and Japan, and Samsung’s fab in Texas are the largest projects receiving government support under these programmes.
The results have been slower and more expensive than initial projections suggested: TSMC’s Arizona fab experienced construction delays and cost overruns, with the most advanced process technology now scheduled for later phases rather than the initial timeline; Intel’s ambitious manufacturing expansion has been affected by its financial challenges; and the workforce development required to staff new fabs is a constraint that subsidies help but don’t fully address. Leading-edge semiconductor manufacturing capability cannot be created in a few years regardless of financial incentives — the human expertise required takes decades to develop.
The Export Control Dimension
US export controls on advanced semiconductors and semiconductor manufacturing equipment to China — significantly tightened in 2022, 2023, and 2024 — represent a deliberate effort to slow China’s ability to manufacture advanced chips domestically. The controls restrict NVIDIA, AMD, and Intel from selling their most capable AI chips to Chinese customers and restrict ASML and other equipment suppliers from shipping leading-edge lithography equipment to China.
The effectiveness of these controls is contested: China has accelerated domestic semiconductor development investment in response, Huawei’s 7nm chip (produced by SMIC using older equipment in ways that weren’t fully anticipated) demonstrated that the controls don’t create an impenetrable capability ceiling, and the controls impose costs on US and allied semiconductor companies that are losing Chinese revenue. The longer-term outcome of the technology restriction versus China’s self-sufficiency drive is one of the most consequential technology policy questions of the current decade.
What This Means for Consumer Electronics
For consumers, semiconductor supply chain dynamics manifest primarily as: price fluctuations for electronics correlated with chip availability and cost, technology generation delays when leading-edge manufacturing capacity constrains production of the most advanced chips, and geographic origin questions for electronics components that have become geopolitical considerations for some procurement decisions.
The chip shortage’s most lasting consumer impact may be the price normalisation at higher levels: the expectation that consumer electronics prices decline year-over-year (as manufacturing efficiency increases) has been disrupted by the period of genuine supply constraint and the capital costs of new fabs that are being passed through supply chains. The $1,200 flagship smartphone that would have been $900 three years earlier reflects partially the supply chain realignment costs alongside the usual premium technology pricing.